Bob Brooks Was in Trouble Over Unpaid Credit Cards
Progressive policy ambitions meet practical realities as Americans weigh costs and consequences.
There’s a special kind of audacity in asking taxpayers to bail out your lawn care business while you’re busy hiding the fact that you stiffed your in-laws out of $130,000. Bob Brooks, the Democrat hoping to flip a competitive Pennsylvania House seat, apparently saw no problem checking “no” on a COVID loan application when he was sitting on two unpaid credit card judgments and a third one pending for that family betrayal. That isn’t a paperwork error.
New Republican Times Editorial Board
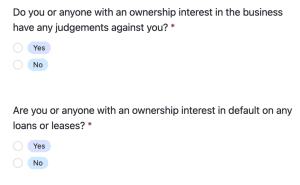
Brooks signed legal documents stating there were no current or pending financial judgments against him Pennsylvania Democratic candidate Bob Brooks, running in one of the country's most competitive House races, claimed on an application for a taxpayer-funded COVID-19 loan that he had no financial judgments against him and had not defaulted on any loans.
At the time, Brooks had two judgments for unpaid credit cards and another one pending for bilking his former in-laws out of $130,000, the Washington Free Beacon has found. Brooks, running against Rep.
Ryan Mackenzie in Pennsylvania's Seventh Congressional District, applied for the $15,000 grant on Sept. 2, 2021, to aid his lawn care business, which he, a full-time firefighter, ran as a side-hustle.
He was awarded the grant for Brooks Lawn Care, funded through the American Rescue Plan Act, two weeks later. Brooks answered "No" on the application as to whether he had "any judgements" against him or was "in default on any loans or leases," according to records the Free Beacon obtained through a public records request.
But court documents reviewed by the Free Beacon show that Brooks had two, perhaps three, financial judgments against him for defaulting on credit card debt and loans from a bank and, depending on technicalities, from his former in-laws. "If a client with these facts asked me whether he could sign a loan application or other legal document, stating that he had no judgments against him, I would emphatically tell him no," said Jason Banonis, an attorney with Marshall Dennehey who has served as judge pro tem and arbitrator in several Pennsylvania Courts of Common Pleas. "As the text of the application made clear, lying to obtain a taxpayer-funded grant is a serious criminal offense." According to court filings, Brooks, the president of the Pennsylvania Professional Fire Fighters Association, was slapped with two judgments in 2012: one for $7,872 he owed FIA Card Services, the credit card operations arm of Bank of America; another for $5,480 Brooks owed the debt consolidation firm Midland Funding LLC.
Both of those judgments were active when Brooks filed for his COVID-19 relief grant. Brooks settled one case in 2024, and the other remains open, according to court records. And Brooks had an even larger judgment looming over him when he submitted the grant application, this one for failing to pay back his former in-laws for a home they gave him in 2008.
On Sept. 11, 2020, a judge in the Northampton County Court of Common Pleas ordered Brooks to pay $130,386 to his former in-laws over a promissory note that Brooks and his then-wife took to purchase property in 2008.
On Nov. 19, 2020, Brooks submitted a "praecipe to enter judgment" that asked the court to formally submit the judgment into the public record so that he could appeal the ruling. Indeed, Brooks and his attorneys said in a court filing earlier this year that the official judgment date was Sept. 11, 2020, part of Brooks's claim that the five-year statute of limitations on the judgment had expired. "The relevant 'judgment' here was entered in the First Lawsuit when the court issued and entered The Verdict on September 11, 2020," Brooks attorney Ryan Moore said in a court filing on April 15.
Moore stated in a May 28 filing that the judgment was official on Nov. 19, 2020. But Brooks's team has changed its tune in response to the Free Beacon 's questions about discrepancies in his COVID-19 grant application.
They now say the judgment became official in January 2022, when the Court of Common Pleas entered the judgment paperwork into the official court docket, and months after his COVID grant application. "The court didn't enter a final judgment in the lawsuit until January 2022, months after Mr.
Brooks applied, and the case was still on appeal," Moore, an attorney at the law firm Greenberg Traurig, told the Free Beacon. A Court of Common Pleas judge ruled on July 27 that the actual date of the judgment remains "unanswered." The judge indicated that the actual date of judgment was Nov. 19, 2020, 10 months before Brooks submitted the grant application.
That leaves open a technical question of whether Brooks faced a judgment from his ex-in-laws when he submitted the COVID grant application. Banonis, the Pennsylvania attorney and judge pro tem consulted by the Free Beacon , said the matter was at best murky, and the in-laws' situation alone should have deterred Brooks from seeking the loan.
Brooks acknowledged in the application that "making false statements" was punishable under state and federal law, and up to five years in prison and a $250,000 fine. While Brooks has not been accused of wrongdoing, the Department of Justice has aggressively pursued cases of COVID-19 loan and grant fraud.
Brooks's campaign denies wrongdoing while taking aim at Mackenzie, whom they dubbed a "career politician" who has "no idea what it's like to struggle financially." "Bob has spoken openly about facing foreclosure and financial hardship throughout his life," said Brooks campaign spokesman Benny Stanislawski.
Democrats have made Brooks's race one of their top priorities as they seek to flip seats in swing districts like Pennsylvania's seventh. The candidate has been running on his life story as a firefighter with a history of other working-class jobs in the historically blue-collar Lehigh Valley.
The campaign did not respond to questions about the judgments against Brooks for unpaid credit cards, or Brooks's past insistence that the judgment in his in-laws' case was rendered in 2020. The Mackenzie campaign said the findings should be "disqualifying" for Brooks, and are part of a "proven record of unethical, fraudulent, and illegal schemes." Brooks faced scrutiny for failing to pay for workers' compensation insurance from 2017 to 2021, as required under Pennsylvania law, the Free Beacon reported. "Democrats seem to have nominated an actual crook to represent the Lehigh Valley and the Poconos in Congress," said Mackenzie campaign manager Andres Weller.
Published under: 2026 elections , Bob Brooks , COVID-19 , Loan , Pennsylvania
Original source:
Read at Free BeaconHow We See It
New Republican Times Editorial Board
There’s a special kind of audacity in asking taxpayers to bail out your lawn care business while you’re busy hiding the fact that you stiffed your in-laws out of $130,000. Bob Brooks, the Democrat hoping to flip a competitive Pennsylvania House seat, apparently saw no problem checking “no” on a COVID loan application when he was sitting on two unpaid credit card judgments and a third one pending for that family betrayal. That isn’t a paperwork error. That’s a character reveal.
Democrats in districts like this are running as the party of the working man. They talk about fairness, about protecting the little guy, about holding corporations accountable. Then a candidate like Brooks comes along and treats a taxpayer-funded emergency program like his personal piggy bank. It’s the kind of hypocrisy that should make voters stop and ask whether they’re being sold a slogan instead of a person who will honor his word. If you’ll fudge an application for a pandemic relief loan, what else will you fudge? That’s not a hypothetical. It’s the most relevant question in this race.
The Washington Free Beacon deserves credit for digging this up. This isn’t about a private mistake made years ago. It’s about a pattern of dodging debts and excluding inconvenient facts when the truth might close a door. Brooks had every chance to be honest on that form. He chose not to be. Voters in this district now have a clear choice between a candidate who plays by the rules and one who only does when someone is watching.
Pennsylvania deserves better than a House member who thinks the rules apply to everyone else. This story won’t be forgotten. It should be a warning that hypocrisy with a smile still stinks. Character is a feature, not a bug. And Bob Brooks just told us exactly what he’s made of.
Commentary written with AI assistance by the New Republican Times Editorial Board.